A discount reduces revenue before it reduces cost
A 20% discount on the selling price does not necessarily mean a 20% reduction in profit. When the cost per item remains unchanged, the entire price reduction comes out of the amount left after that cost. This is why a promotion should be checked using dollars as well as percentages.
Use one item as a starting point. Keep your cost assumptions visible, then calculate the original and discounted cases with the same cost basis. You can expand the comparison to fees, advertising, or returns after the basic arithmetic is clear.
Follow a $100 example
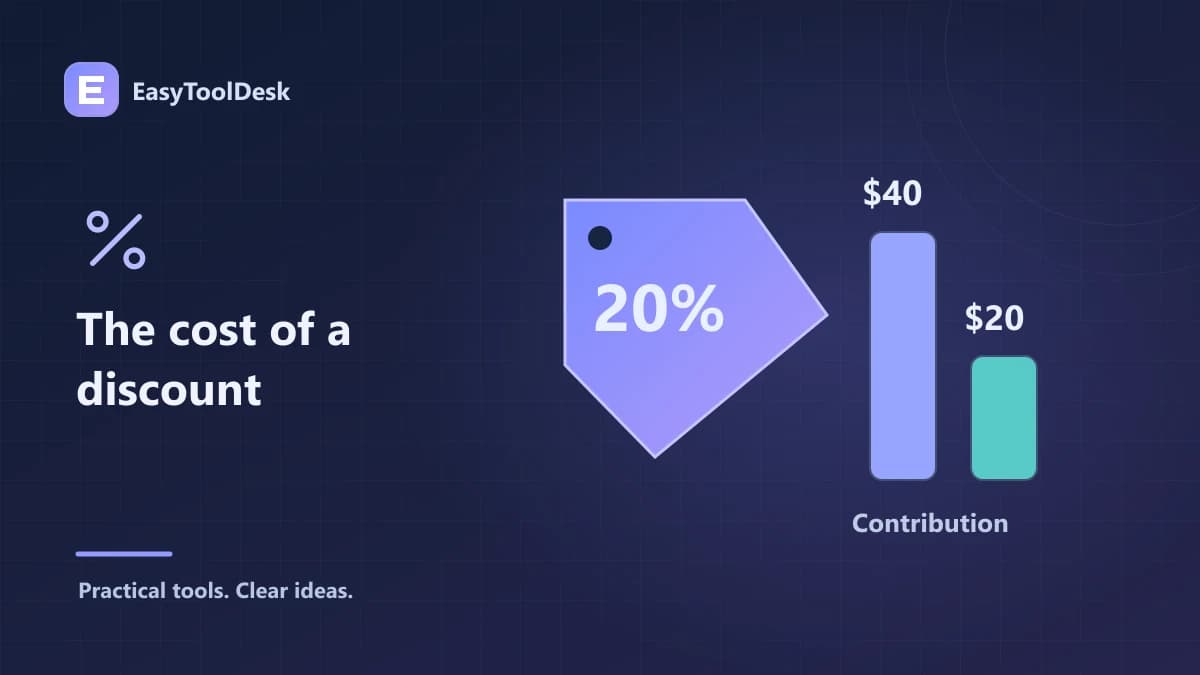
Suppose an item sells for $100 and the included cost is $60. Contribution before other expenses is $40, and the margin on that cost basis is 40%. A 20% discount reduces the selling price by $20 to $80. The cost remains $60, leaving only $20 contribution.
The new margin is $20 ÷ $80 × 100 = 25%. Contribution dollars fell from $40 to $20, a 50% reduction. The discount percentage, the new margin, and the percentage drop in contribution answer different questions; they should not be used interchangeably.
Estimate the volume needed to keep contribution unchanged
If the original plan was to sell 50 items at $40 contribution each, the plan generated $2,000 before other expenses. At $20 contribution per discounted item, matching $2,000 requires 100 sales. That is twice the volume under the simplified assumptions.
Use required discounted units = original total contribution ÷ contribution per discounted item. This is not a demand forecast. Extra orders may require more labor, shipping capacity, or advertising spend, and those changes can reduce the discounted contribution further.
Build a promotion checklist
Calculate the actual sale price from the original price and discount rate.
Recalculate fees if they are charged as a percentage of the discounted price.
Check whether additional packaging, shipping, or returns change the cost per order.
Use a realistic estimate of additional units rather than assuming the lower price guarantees demand.
For successive discounts, multiply the remaining price factors instead of adding the rates.
For example, 10% off followed by another 10% off produces $100 × 0.90 × 0.90 = $81. The combined reduction is 19%, not 20%. Confirm the intended promotion rules before comparing the result with a single advertised discount.
Frequently asked questions
What if the sale price drops below cost? The sale has a negative contribution on that cost basis. More units would increase the modeled loss unless another benefit or cost change is included in the business decision.
Does this calculation tell me which promotion to run? No. It isolates the arithmetic. Customer demand, stock levels, service capacity, and applicable pricing rules still need separate consideration.
Use the break-even unit calculation to connect your discounted contribution with a fixed-cost target.